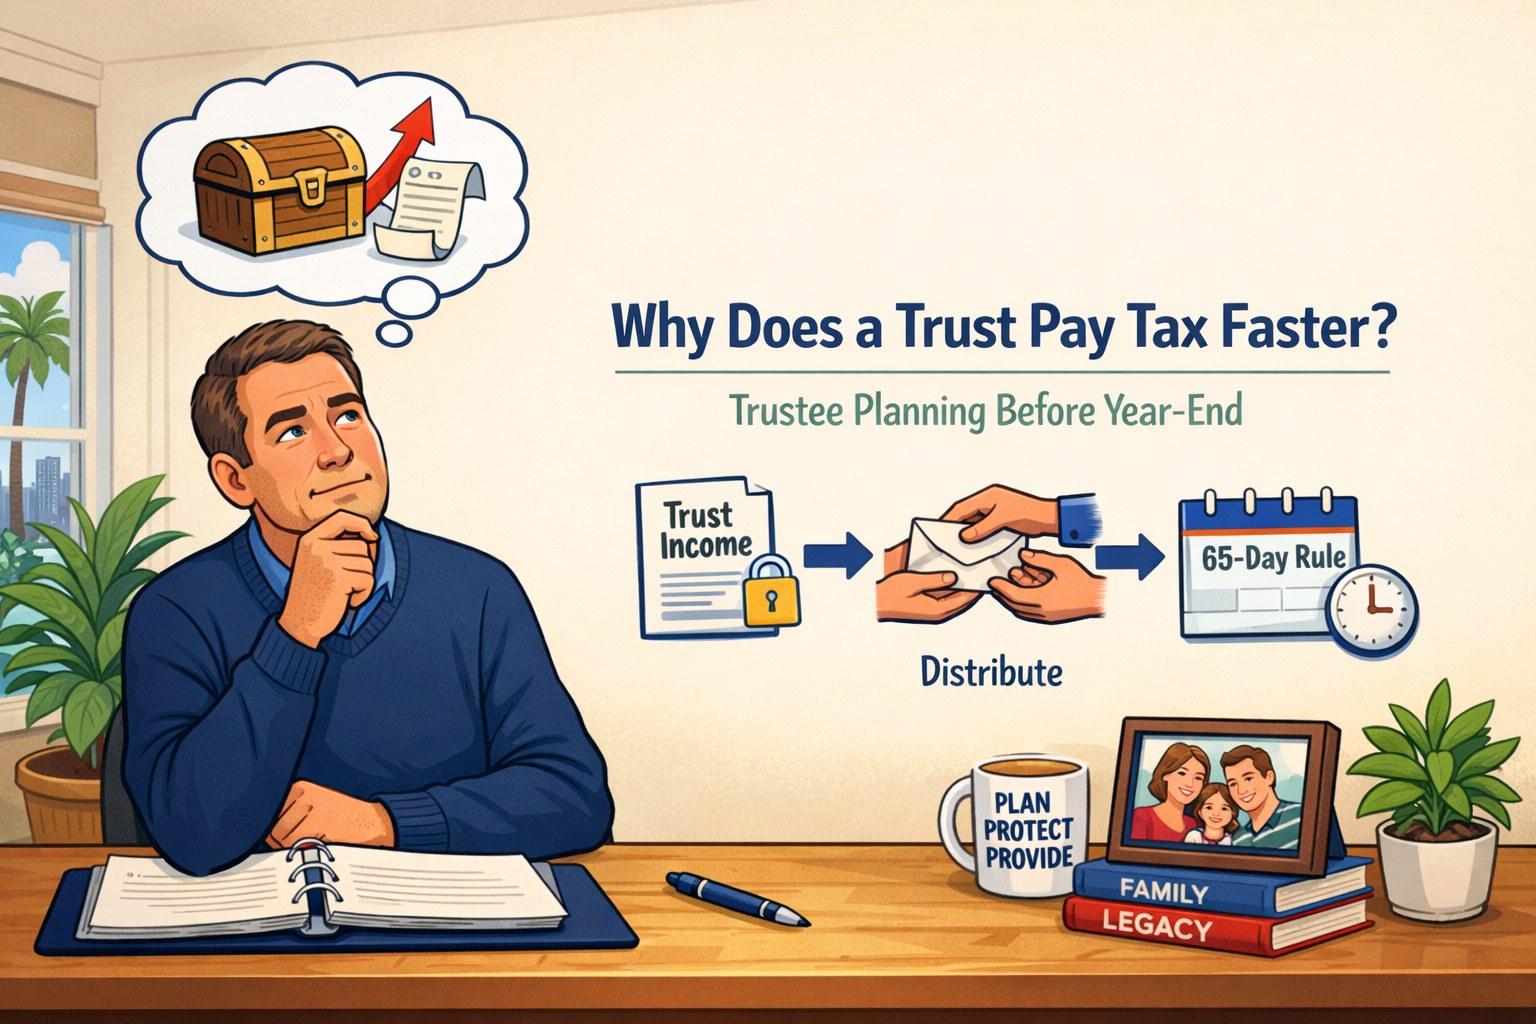
Under the 2026 trust income tax rates, a trust or estate that keeps its income pays the top 37% federal rate on taxable income over $16,000. A single person does not reach 37% until taxable income passes $640,600. The 3.8% net investment income tax also starts at roughly that same low level for a trust, compared with $200,000 or $250,000 for individuals. The good news is that income a trust properly distributes is usually taxed to the beneficiaries instead, and trustees have until early March 2027 to make distributions that count for 2026.
Trust income tax rates in 2026 compared with yours
Estates and trusts have four rates (10%, 24%, 35% and 37%), and the brackets are very narrow. For 2026, the IRS tables in Rev. Proc. 2025-32 show the 37% rate applying to trust and estate taxable income over $16,000.
The 3.8% net investment income tax (NIIT) follows the same line. For a trust or estate, it applies to the lesser of its undistributed net investment income or its adjusted gross income above the point where the top bracket begins (26 U.S.C. § 1411(a)(2)). For individuals, the NIIT starts at modified adjusted gross income of $200,000 (single) or $250,000 (married filing jointly) (26 U.S.C. § 1411(b)). Those individual amounts are not indexed for inflation.
- 37% rate begins (taxable income over) — Trust or estate: $16,000; Single filer: $640,600; Married filing jointly: $768,700
- 3.8% NIIT begins (income over) — Trust or estate: $16,000 (AGI); Single filer: $200,000 (MAGI); Married filing jointly: $250,000 (MAGI)
- 20% capital gains rate begins (taxable income over) — Trust or estate: $16,250; Single filer: $545,500; Married filing jointly: $613,700
- 0% capital gains rate ends (taxable income at) — Trust or estate: $3,300; Single filer: $49,450; Married filing jointly: $98,900
To see what this means in dollars, take $50,000 of ordinary taxable income, such as interest. Under the 2026 tables, a trust keeping that income owes $16,431 in regular federal income tax, before any NIIT. The same $50,000 of taxable income for a single individual produces $5,752 of tax.
Which trusts face these rates
These compressed brackets mainly affect non-grantor trusts and estates, the ones that file their own Form 1041 and pay their own tax.
A revocable living trust is different while its creator is alive. Because the creator can take the property back, the trust is a "grantor trust" and its income is reported on the creator's own return (26 U.S.C. §§ 671, 676). Grantor trusts are not subject to the trust-level NIIT either.
The picture changes at death. A revocable trust can no longer be revoked, and it generally becomes a separate taxpayer. A trustee and personal representative can elect to have a qualified revocable trust treated as part of the probate estate for income tax purposes for a limited period (26 U.S.C. § 645, made on Form 8855). One practical benefit: an estate may choose a fiscal year rather than the calendar year that most trusts must use.
So the trusts to watch are irrevocable trusts that are not grantor trusts, trusts that continue for children or grandchildren after a parent's death, and estates still in administration.
How distributions move income to beneficiaries
The income tax rules for trusts are built around one idea: income is taxed once, either to the trust or to the beneficiaries who receive it.
When a trust distributes money, it generally gets a deduction for the distribution, and the beneficiary reports that income on their own return (26 U.S.C. §§ 651, 661, 662). The beneficiary receives a Schedule K-1 showing what to report. The income keeps its character, so interest stays interest and qualified dividends stay qualified dividends.
The ceiling on this shift is distributable net income, or DNI (26 U.S.C. § 643(a)). DNI is roughly the trust's taxable income for the year, with a few adjustments. A distribution larger than DNI does not carry out more income; the excess is generally a tax-free distribution of principal to the beneficiary.
The capital gains catch
Capital gains are usually left out of DNI. When a trustee sells stock or real estate at a gain, that gain is ordinarily allocated to principal and taxed to the trust, even if the trustee distributes cash that year (Treas. Reg. § 1.643(a)-3(a)). Florida's principal and income law generally allocates the proceeds of selling a principal asset to principal (Fla. Stat. § 738.404(2)).
Gains can be included in DNI in limited cases: when the trust document and Florida law allocate them to income, when the trustee consistently treats them as distributed, or when they are actually distributed or used to determine a distribution (Treas. Reg. § 1.643(a)-3(b)). Whether any of these fits a given trust depends on the document and the trustee's past practice.
The 65-day rule: a second chance after December 31
Trustees often do not know a trust's final income until statements arrive in January. The tax code allows for that.
Under the 65-day rule, a trustee of a complex trust or the executor of an estate may elect to treat distributions made in the first 65 days of the new year as if they were made on the last day of the prior year (26 U.S.C. § 663(b)). For a calendar-year trust's 2026 tax year, that window runs from January 1 through March 6, 2027.
Key points:
- The 65th day is a Saturday. March 6, 2027 falls on a weekend, so plan to complete distributions by Friday, March 5, 2027.
- The election is made on the return. The trustee checks the box for the section 663(b) election on the trust's Form 1041. The election must be made by the return's due date, including extensions, and it becomes irrevocable once that deadline passes (Treas. Reg. § 1.663(b)-2(a)).
- It is year-by-year. An election covers only the year for which it is made (Treas. Reg. § 1.663(b)-1(a)(2)).
- There is a cap. The amount you can elect is limited to the greater of the trust's accounting income or its DNI for the year, reduced by distributions already made during that year.
- The beneficiary reports it for the earlier year. A distribution treated as made on December 31, 2026 is reported by the beneficiary on their 2026 return.
For calendar-year trusts and estates, Form 1041 is due on the 15th day of April after year-end (26 U.S.C. § 6072(a)), which for 2026 returns is April 15, 2027.
Saving tax is not the only test
Shifting income to beneficiaries is often sensible, but a trustee cannot make a distribution just because it lowers the tax bill. Several limits apply.
The trust document controls. A Florida trustee must administer the trust in good faith, according to its terms and purposes and the interests of the beneficiaries (Fla. Stat. § 736.0801). If the trust allows distributions only for a beneficiary's health or education, a tax-driven distribution beyond that may not be permitted.
Discretion must be exercised in good faith. Even broad language like "sole" or "absolute" discretion does not excuse the trustee from acting in good faith and in line with the trust's purposes (Fla. Stat. § 736.0814(1)). A trustee who is also a beneficiary faces added limits on discretionary distributions to themselves (Fla. Stat. § 736.0814(2)).
Protection ends at distribution. A spendthrift clause keeps a beneficiary's creditors from reaching trust money only until the beneficiary receives it (Fla. Stat. § 736.0502(3)). A beneficiary facing a lawsuit, divorce, bankruptcy, or spending problems may be far better served by money staying in the trust, even at a higher tax cost.
The beneficiary's own tax picture matters. Income carried out to a beneficiary in a high bracket, or one already above the $200,000 or $250,000 NIIT threshold, may save little. Distributed net investment income keeps its character for the beneficiary's own NIIT calculation (Treas. Reg. § 1.1411-3(e)(3)(ii)). Florida has no personal income tax, but a beneficiary living in another state may owe that state's income tax.
A practical year-end sequence
Before December 31, confirm whether the trust is a grantor or non-grantor trust, estimate its 2026 income, DNI and capital gains, and reread the distribution standard in the trust document. Then weigh each beneficiary's needs, creditor exposure and tax bracket. If you make distributions in January or February, tell your tax preparer so the 65-day election is made on the Form 1041, and write down why each distribution fits the trust's terms. Good records also make your trust accountings easier to prepare and explain.
Our page on trustee responsibilities covers these duties in more detail.
Frequently asked questions
If a trust distributes all of its income, does it still file a return?
Usually yes. A trust taxed under the regular trust rules must file Form 1041 if it has any taxable income or gross income of $600 or more, among other triggers. Distributions reduce the trust's tax, not its filing obligation.
Can an estate use a different tax year than a trust?
Yes. A trust generally must use the calendar year (26 U.S.C. § 644). An estate's first tax year can be any period of 12 months or less ending on the last day of a month, so a personal representative can choose a fiscal year when the first return is filed.
What if the trust must pay out all its income every year?
A trust whose terms require all income to be distributed currently gets a deduction for that income (26 U.S.C. § 651), and the beneficiary is taxed on it whether or not the trustee actually pays it out on time (26 U.S.C. § 662(a)(1)). The compressed brackets matter most for trusts that can accumulate income.
How we can help
Year-end trust decisions involve tax law, the trust document and the trustee's duties to every beneficiary, and the 65-day window closes quickly. Yergey & Yergey, P.A. has served Central Florida families since 1928, and David A. Yergey III holds an LL.M. in Taxation. If you are a trustee or personal representative weighing distributions for 2026, we welcome you to schedule a consultation with our Orlando office, in person, by phone or by video.
IRS Circular 230 Disclosure: To ensure compliance with requirements imposed by the IRS, any U.S. federal tax advice contained in this communication is not intended or written to be used, and cannot be used, for the purpose of (i) avoiding penalties under the Internal Revenue Code, or (ii) promoting, marketing, or recommending to another party any transaction or matter addressed herein.